GOV–4 - Statement on due diligence
🗂️ ESRS 2 General Disclosures, page 8
-
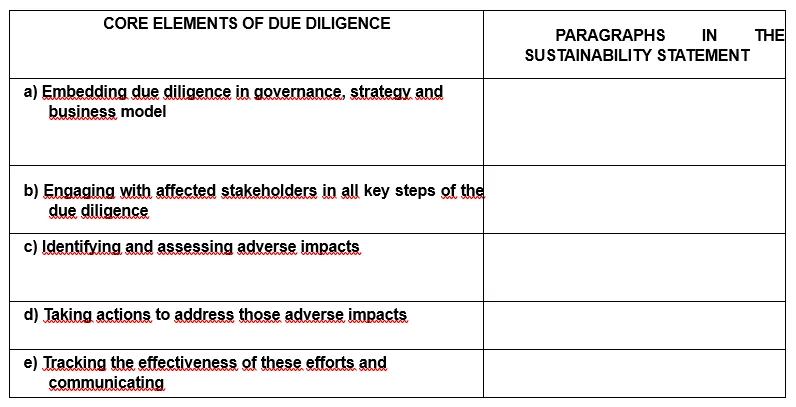
The undertaking shall disclose a mapping of the information provided in its sustainability statement about the due diligence process.
-
The objective of this Disclosure Requirement is to facilitate an understanding of the undertaking’s due diligence process with regard to sustainability matters.
-
The main aspects and steps of due diligence referred to under ESRS 1 chapter 4 Due diligence are related to a number of cross-cutting and topical Disclosure Requirements under the ESRS. The undertaking shall provide a mapping that explains how and where its application of the main aspects and steps of the due diligence process are reflected in its sustainability statement, to allow a depiction of the actual practices of the undertaking with regard to due diligence.
-
This disclosure requirement does not mandate any specific behavioural requirements with regard to due diligence actions and does not extend or modify the role of administrative, management and supervisory bodies as mandated by other legislation or regulation.
Application Requirements
Section titled “Application Requirements”AR 8. The mapping required by paragraph 30 may be presented in the form of a table, crossreferencing the core elements of due diligence, for impacts on people and the environment, to the relevant disclosures in the undertaking’s sustainability statement, as set out below.
AR 9. The undertaking may include additional columns to the table below to clearly identify those disclosures that relate to impacts on people and/or the environment given that, in some cases, more than one disclosure may provide information about the same due diligence step.
AR 10. The main references in the international instruments of the UN Guiding Principles on Business and Human Rights and the OECD Guidelines for Multinational Enterprises to the core elements of the due diligence process are listed in ESRS 1 chapter 4.